

Deferit: Split Bills, Pay in 4 analysis by Appwee
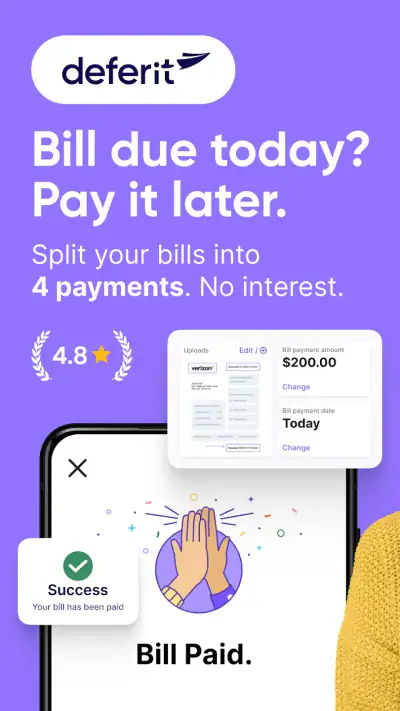
When a bill arrives at the wrong moment, the problem is often timing rather than the total amount. That is the situation Deferit: Split Bills, Pay in 4 is built around. It is a finance app from Deferit that lets eligible users divide bills into four smaller payments without interest, rather than handling the full amount in one go. I found the idea immediately understandable, and the first impression is strong because it focuses on a familiar household problem instead of trying to become an all-purpose money manager.
The important question, though, is not whether splitting one bill feels useful. It does. The better question is whether the app still deserves a regular place on your phone after the initial relief wears off. My view is that it can, especially for people who receive income on a predictable schedule but face bills clustered together. It is less convincing as a permanent solution for someone whose monthly budget is already short, because dividing a payment changes its timing rather than removing the obligation.
From quick relief to a lasting money habit
Why the first week feels so appealing
The first-week appeal comes from simplicity. Instead of looking at a large bill as one immediate hit, I can think about four smaller commitments. That mental shift matters. A utility bill, phone bill, insurance payment, or another regular expense can feel less disruptive when it is spread across several scheduled payments. The app’s core promise is easy to understand, and that is a real advantage in a category where financial products often bury the useful part under complicated language.
Deferit is free to download and has an Everyone content rating, so it is positioned as an accessible tool rather than a specialist service for experienced investors or credit users. It runs on Android devices using version 7.0 or later. The current version is 3.0.6, which makes checking compatibility before installing worthwhile if you use an older phone. On iOS, the practical experience will depend on the device and the app’s current store availability, but the service is clearly designed for everyday bill management rather than advanced financial analysis.
My first useful test for an app like this is whether I can explain its purpose in one sentence to a friend. Here, I can: use it when a bill is due now but paying it in four parts would fit my cash flow better. That clarity reduces the chance of treating it like a vague credit product. It also helps set the right expectation: the app is a payment-timing tool, not a way to make an unaffordable bill affordable forever.
A realistic example would be a household that receives income twice a month while several bills arrive during the same week. Rather than letting the account balance fall sharply on one date, the user may prefer four smaller deductions arranged around the bill. The benefit is not only mathematical. It can make the rest of the week easier to plan, leaving room for groceries, transport, and other unavoidable spending.
The detail that matters before committing
Before using any pay-in-four service, I would slow down and read the payment schedule shown for each bill. “No interest” is helpful, but it does not mean the arrangement is consequence-free. The user still has to keep enough money available for every installment. I would also check the total amount being handled, the dates of the upcoming payments, and whether the plan fits alongside existing commitments. The most useful habit is to treat the four payments as already spent in the budget, even though the money has not left the account yet.
This is one of the less obvious trade-offs. Splitting a bill can improve short-term cash flow while making the next few weeks more crowded. If I use the service for several bills at once, each individual installment may look manageable, but the combined schedule can become difficult to follow. The app may make the first payment feel lighter, yet the real test is whether the later payments remain comfortable when another bill arrives.
For that reason, I would begin with one recurring bill rather than moving everything into the app immediately. That creates a small trial without turning the entire household budget into a network of overlapping obligations. After a full cycle, I could judge whether the reminders, dates, and payment pattern genuinely help or simply add another layer to monitor.
What makes the service different from usual alternatives
The usual alternative is to pay the bill directly from a current account on its due date. That is cleaner and usually better when the money is already available. Another option is to use a credit card, but that can introduce interest or encourage a balance to roll over. A traditional personal loan is generally too heavy for a single household bill, while asking a provider for a different due date may not be possible.
Deferit sits between those choices. Its value is strongest when the bill is legitimate and manageable, but the payment date does not match the user’s income rhythm. It is not automatically better than paying directly; it is better for a specific timing problem. That distinction is important because the app’s convenience can otherwise encourage users to add a payment plan where no plan was needed.
The service has attracted a substantial audience, with over one million installs, a 4.6 average from around twenty thousand ratings, and roughly two thousand reviews. Those figures suggest that the basic idea resonates with many people, but they do not answer the personal question of whether the schedule will suit my budget. I would use the popularity as reassurance that the concept is established, not as a substitute for checking my own cash flow.
Month-to-month value depends on repetition
After the novelty fades, the app’s value comes from recurring discipline. A one-time split can be useful during an unusually expensive month, but the stronger use case is a repeating bill that is predictable enough to plan for. If I know the same type of expense returns regularly, I can decide in advance whether splitting it supports my budget or merely delays pressure until later.
This is where the app can earn lasting space. A good monthly routine would involve reviewing upcoming installments at the same time as checking the rest of the household budget. I would not open the app only when a bill becomes urgent. Instead, I would use it as one small part of a weekly money check: look at what is due, confirm that the next payments are covered, and avoid starting another plan simply because the current screen looks calm.
One practical technique is to keep a separate note showing the total of all scheduled installments across the month. That number is more meaningful than looking at each payment in isolation. It exposes the hidden cost of convenience: several “small” payments can still form a large outgoing amount. This habit also makes it easier to decide when to pay a bill normally again.
The app is particularly suitable for people with regular income but uneven bill timing. Someone paid every two weeks may find four smaller deductions easier to absorb than one large withdrawal. It may also help a household that wants to avoid repeatedly dipping into an emergency buffer for ordinary expenses. However, a person with unpredictable income should be more cautious. If the next paycheck is uncertain, four future commitments can be more stressful than one bill that is postponed or renegotiated directly with the provider.
Where recurring value starts to weaken
The long-term benefit becomes less clear if the user needs to split every bill, every month. At that point, the app may be compensating for a structural budget gap rather than smoothing temporary timing issues. The distinction is easy to miss because each plan can feel reasonable on its own. I would treat repeated reliance as a signal to review income, fixed costs, and due dates, not as proof that I should keep adding plans.
There is also a planning cost. A direct bill payment has one obvious event. A split arrangement creates several dates that must remain visible. If the app presents those dates clearly and I check them regularly, the extra structure may be worthwhile. If I ignore notifications, change bank balances often, or manage money across several accounts, the arrangement can become tiring.
This is the main maintenance burden: the user must remember that a completed first payment does not mean the bill is finished. I would keep notifications enabled if the app offers them, but I would still rely on my own budget rather than assuming a reminder will solve everything. I would also avoid using the service while my account is close to zero, because even a small unexpected expense could interfere with a scheduled installment.
Small sources of fatigue that matter over time
Financial apps often feel effortless during the first transaction and more demanding after several weeks. The fatigue here comes from repetition, not necessarily from the central idea. Every active plan becomes another item to review. If I use the app for multiple household bills, I need to know which payments are pending, which have cleared, and how much of the month’s income is already committed.
That makes organization essential. I would name or record each bill in a simple personal budget, especially if several plans have similar installment amounts. I would also review the schedule before making a large discretionary purchase. The useful question is not “Can I afford this today?” but “Will this still be comfortable after the next scheduled deductions?” That change in thinking is one of the most valuable ways to use the app responsibly.
Another potential source of frustration is expectation. A user may download the app hoping it will remove financial stress, but payment splitting cannot fix a bill that is too large for the monthly budget. It may provide breathing room, yet the obligation remains. Anyone who expects a permanent reduction in expenses is likely to feel disappointed. Anyone who wants a clearer way to distribute a manageable expense may find the tool more worthwhile.
I would also avoid treating the service as an emergency fund replacement. An emergency fund remains flexible and can cover many kinds of unexpected costs. A split-bill arrangement is tied to a particular payment and creates future dates. Those are different jobs. Keeping that distinction clear prevents the app from becoming the default answer to every financial surprise.
Who should use it and who should skip it
I would recommend trying Deferit if your income is fairly predictable, your bills are manageable in total, and your main difficulty is that due dates arrive together. It can be especially useful for someone who wants to smooth a recurring expense without paying interest, provided the four future payments are fully included in the budget.
I would be more hesitant if you already have several buy-now-pay-later commitments, regularly miss payments, or rely on one paycheck to cover the next one. Adding another schedule may increase pressure even when the individual installments look small. In that situation, contacting the bill provider, changing a due date, using a carefully planned direct payment, or seeking independent budgeting help may be better.
It is also not the best choice for someone who has the full amount available and values maximum simplicity. Paying the provider directly means fewer moving parts. Likewise, if your income changes sharply from week to week, a fixed four-payment pattern may not match reality. The app should serve a stable plan, not replace one.
My long-term verdict
After the first-week convenience has worn off, I think the app earns a place for a specific kind of user: someone who needs better timing, not more spending power. Its continuing value comes from making a manageable bill easier to distribute and easier to plan around. The no-interest structure is appealing, but the responsible use of it depends on treating every installment as a real commitment from the moment the plan begins.
Deferit is free, focused, and straightforward enough to test without a long learning curve. Deferit, developed by Deferit, has built a recognizable finance tool around one clear problem rather than overwhelming users with unrelated features. That focus is its strength. It is also its limit, because it will not replace a complete budget, emergency savings, or direct communication with a bill provider.
My recommendation is to start narrowly: choose one suitable bill, map all four payments against your income, and review the result after the cycle ends. If the arrangement reduces stress without causing later shortages, it may become a useful monthly habit. If it only postpones the same problem, return to direct payment or look for a broader budgeting solution. The lasting value is not in splitting every bill; it is in using the split only when the timing genuinely helps.
Gallery
Deferit: Split Bills, Pay in 4 Pros and Cons
- Splits eligible bills into manageable installments.
- Helps avoid late fees by scheduling payments.
- Clear payment tracking within the app.
- May support credit-building features for eligible users.
- Useful for users with irregular monthly cash flow.
- Approval and spending limits vary by user.
- Some plans may include membership or processing fees.
- Missed payments can lead to penalties or account restrictions.
- Not every bill or provider may be supported.
- Requires access to a linked payment method.
Deferit: Split Bills, Pay in 4 Frequently Asked Questions
What is Deferit: Split Bills, Pay in 4?
Deferit is a bill-payment and budgeting app designed to help users manage selected bills through flexible payment options. Depending on eligibility and location, the service may allow you to pay a bill in installments or split certain purchases into four payments. The app is intended to improve short-term cash flow, but it does not eliminate the total amount owed, and repayment terms, fees, limits, and supported billers can vary.
How does Deferit’s Pay in 4 or bill-splitting feature work?
After creating an account and completing any required verification, you generally choose an eligible bill or purchase, review the available repayment schedule, and authorize Deferit to make or arrange the payment. You then repay the amount according to the displayed installments. Before confirming, carefully check the payment dates, total cost, possible service charges, and consequences of a missed payment, since the exact process may differ by region and account.
Is Deferit available to everyone, and what do I need to sign up?
Availability depends on your country, state or territory, age, identity, payment method, and other eligibility requirements. Registration may require personal information, a valid mobile number, identification details, and a supported debit card or bank account. Approval is not guaranteed, and the app may assess your account before offering a limit or installment plan. Always review the current eligibility rules inside the app or on Deferit’s official website.
Are there fees or interest charges when using Deferit?
The cost of using Deferit depends on the product, repayment option, location, and plan shown at checkout or before a bill is submitted. Some services may involve membership, convenience, late, or other fees, while certain plans may advertise no traditional interest. Do not rely only on promotional wording: review the full repayment amount, recurring charges, due dates, and cancellation terms before accepting an offer.
What happens if I miss a Deferit payment or need help with a bill?
A missed installment can potentially result in late fees, account restrictions, unsuccessful bill payments, or other consequences described in your agreement. If you expect a problem, contact Deferit support as soon as possible rather than waiting until the due date has passed. Keep enough funds available in your linked payment method, monitor notifications, and remember that using the app does not replace the need to pay your bills on time.














